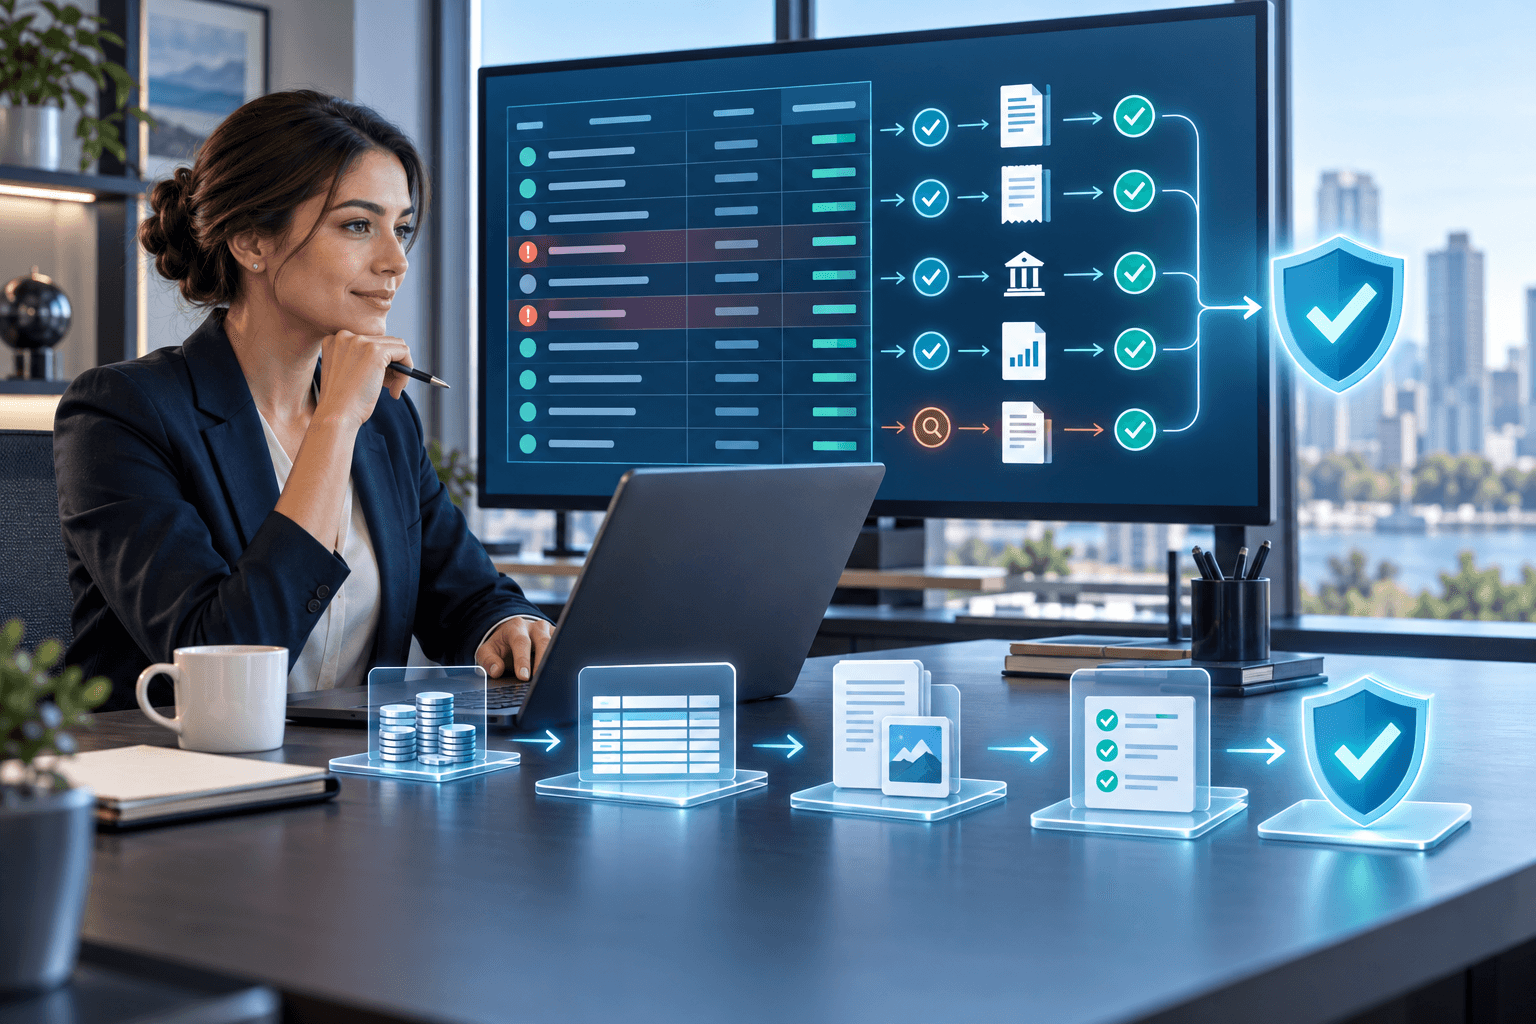
01Know who may review the booksUnderstand what a lender, auditor, tax office or buyer is likely to check.
02Fix the common problemsLook for unreconciled transactions, unclear accounts, missing details and old balances.
03Keep the paperworkRetain invoices, receipts, approvals and notes that explain the figures.
04Make it a monthly habitAssign each check and correct confirmed errors properly in Xero.
1. Know who may review the books
Sooner or later, someone outside your business may look closely at your accounts. A bank may review a loan application. An auditor or tax office may test a transaction. An investor or buyer may examine the quality of the records before making a decision.
These reviews increasingly use the accounting information itself, not only a polished report. The reviewer may see the transactions, account codes, contact details and attachments behind the totals. A tidy report cannot hide untidy books underneath.
Being ready means three simple things: the numbers are correct, similar transactions are coded the same way, and you can explain anything unusual. It is a habit you maintain, not a document you rush together when someone asks.
2. Fix the common problems
Each month, look for bank transactions that have not been reconciled, amounts sitting in suspense or uncategorised accounts, old invoices that should have been paid or written off, and transactions with no receipt or explanation.
A suspense account is a temporary holding account for transactions that have not yet been classified. It can be useful for a short time, but an old or growing balance tells a reviewer that some transactions have not been resolved.
Also check whether the same kind of expense is being posted to different accounts, and whether important customer or supplier details are missing. The goal is not to make the numbers look better. It is to make the genuine numbers easy to check.
3. Keep the paperwork behind each number
When you move figures from Xero into Excel, note which company and period they came from, what was included or left out, and who reviewed the result. Then another person can trace a number back to Xero.
Keep the invoice, receipt, contract or approval that supports an unusual transaction. Add a short note where the reason would not be obvious to someone outside the business. Do not rely on one person's memory.
If you find a mistake, correct it properly in Xero or ask your bookkeeper or accountant to do so. Changing only the spreadsheet leaves the official accounting record wrong.
4. Make it a monthly habit
Set aside a regular time to complete the checklist. Decide who performs each check and who reviews the important exceptions. A short monthly review is usually easier than a large clean-up during a loan application or audit.
Focus first on items that could change a decision: unreconciled cash, unexplained loans, overdue tax balances, large uncategorised expenses and transactions without support. Record what was checked and what still needs action.
Readiness does not guarantee a loan, audit outcome or sale. It does mean the reviewer receives records that are easier to understand and that your team spends less time reconstructing explanations under pressure.
WORKED EXAMPLE
Worked example: an equipment-loan application
A café owner applies for finance for a new coffee roaster. The bank reviews the Xero records and finds $18,000 in Uncategorised Expenses.
What the bank sees
Why it causes a delay
What a monthly check would have done
$18,000 with no clear account
The bank cannot tell whether it is normal operating cost, equipment or a personal item
Classify each transaction and attach the supporting receipt
Several old unpaid invoices
Reported debtors may not reflect what is actually collectible
Confirm payment, write-off or collection status each month
Missing descriptions
The owner must reconstruct the purpose during the application
Add a useful description when the transaction is reviewed
WORKED EXAMPLE
Who may look at the records
Reviewer
What they may check
Bank or lender
Cash flow, existing debt, overdue amounts, unusual expenses and whether the records support the application
Auditor
Whether recorded transactions exist, are classified correctly and have supporting evidence
Tax office or other authority
Tax-related transactions, source documents, dates and consistency with lodged information
Investor or buyer
Earnings quality, working capital, unusual balances and whether the records can be relied on
PUT IT INTO PRACTICE
Monthly record-readiness checklist
Reconcile every active bank and credit-card account.
Clear old amounts from suspense and uncategorised accounts.
Review overdue customer and supplier invoices.
Check large or unusual transactions and add an explanation.
Attach missing invoices, receipts and approvals.
Use the same accounts for the same kinds of transactions.
Review loans, director balances, tax accounts and payroll liabilities.
Record who completed the checks and what remains open.
COMMON QUESTIONS
Questions people ask about this work
How long should a monthly check take?
It depends on transaction volume and how clean the records already are. A small business with current reconciliations may need less than an hour; a backlog can take much longer. Start with the highest-risk balances.
Do I need an accountant to do this?
A trained bookkeeper or business owner can perform many routine checks. Ask an accountant about uncertain tax treatment, material adjustments, loan classifications or anything that may affect formal reporting.
What is a suspense account, and why does it matter?
It is a temporary holding account for an amount that has not been classified. Old balances matter because a reviewer cannot tell what they represent or whether the accounts are complete.
Does clean data guarantee that a bank will approve my application?
No. The lender makes its own decision. Clean, supported records reduce avoidable questions and help the lender understand the business more quickly.
Written and reviewed by the KalkuleX product team.